

Suppose you are buying a $1,250,000 home with $250,000 down, so the loan is $1,000,000 on a 30-year fixed term. Two offers arrive. Offer A is 6.500% with no points, and Offer B is 6.375% with one point ($10,000 up front). The monthly principal and interest is about $6,321 on A and about $6,239 on B, a difference of roughly $82 a month, so the point takes about ten years to repay. Illustrative only, not a quote. The lower number is not automatically the lower total cost, and that is the question behind choosing between me and Rocket Mortgage.
I’m Duane Buziak, and I shop your jumbo loan across multiple wholesale lenders as a broker. Rocket Mortgage is a single-company originator with a strong digital process. If your file is clean and you want one online experience, Rocket is a reasonable fit. If your file is complex or you want several jumbo offers compared on total cost, a broker is built for that.
- A broker compares options across several wholesale lenders; Rocket shows you Rocket’s own products and pricing.
- Compare Loan Estimates line by line on APR, points, credits and reserves, not on the headline number.
- Self-employed, asset-based and second-home files depend on investor guidelines, which differ by investor.
- A NoTouch Credit Pull soft pull pre-approval shows a jumbo path before any hard inquiry.
- I am licensed in only 11 jurisdictions, so confirm your property’s state first.
At a Glance: Two Ways to Finance a Jumbo Loan
- Duane Buziak (Premium Mortgages): independent broker (NMLS #1110647) who shops jumbo, high-balance and second-home loans across multiple wholesale lenders; compensation is disclosed on your Loan Estimate and details are on the website; best for complex jumbo files and buyers who want several lenders compared; limitation: a broker does not fund or service the loan, and I am licensed only in VA, FL, TN, GA, DC, NC, SC, MD, TX, KY and WV.
- Rocket Mortgage: large national retail originator with a digital-first application; pricing is on its website and varies by file; best for clean, standard files and buyers who want one online process; limitation: you see only that company’s own products and pricing.
Duane Buziak: A Broker Who Shops Jumbo Loans Across Wholesale Lenders
I am a licensed mortgage broker, Duane Buziak at Premium Mortgages (NMLS #1110647), not a lender. I arrange your financing by comparing options across multiple wholesale lenders, then help you choose the one whose terms fit your file and total cost. A wholesale lender, not I, funds the loan.
My proof points are plain: 5.0 reviews, 2,000+ verified reviews across all platforms, and licensing in 11 jurisdictions: Virginia, Florida, Tennessee, Georgia, the District of Columbia, North Carolina, South Carolina, Maryland, Texas, Kentucky and West Virginia. Recognition includes Scotsman Guide Top Originator 2025 and 2026, VA Broker of the Year 2024 and 2025, and UWM PRO ELITE 2025. If your property is outside those jurisdictions, I cannot arrange your loan, and I would rather say so at the start.
What I do distinctively is pair multi-lender comparison with the NoTouch Credit Pull soft pull pre-approval. You can see a jumbo path, including what documents a given investor will want, before any hard credit inquiry. I also work with self-employed, asset-based, second-home and investor files, and with Realtors who need a clear read on a client’s financing before an offer.
Pricing
I do not publish a fixed fee here. A broker is compensated in ways that are disclosed to you in writing, and the Loan Estimate shows the origination charges. Ask me for the compensation disclosure on your specific loan before you commit. Costs move with loan size, points, lender credits and the investor chosen.
The limitations are real. I am a small team, so there is no branded national app of the kind Rocket offers. I do not fund or service loans, and I serve only the licensed jurisdictions above.
Pros:
- Several lender options from one application
- One named loan officer for the whole transaction
- Soft pull pre-approval protects your credit score early
- Flexibility for complex income and asset files
Cons:
- Smaller team and no branded national app
- Limited to 11 licensed jurisdictions
- Does not fund or service the loan
Best for: jumbo buyers with complex files who want several lenders compared on total cost.
Rocket Mortgage: A Large Digital-First Originator With Jumbo Options
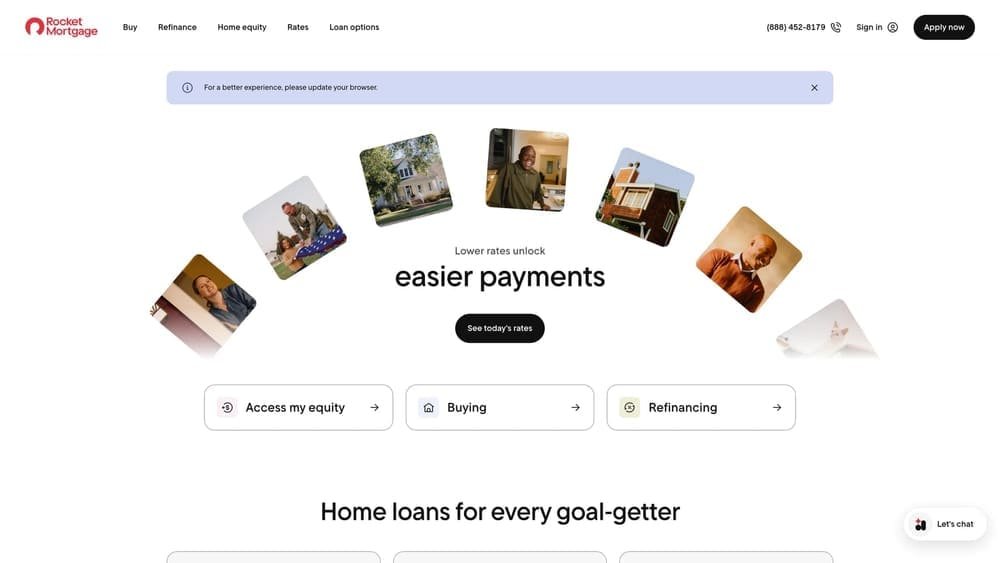
Rocket Mortgage is a large national retail originator built around an online application, a progress dashboard and document upload. It offers jumbo financing alongside conforming, FHA and VA programs. Credit is due: its process polish, technology and brand scale are among the most developed in the industry, and many buyers value the simplicity of one company handling everything from application to closing.
Jumbo terms are the part to verify directly. Minimum loan amounts, down payment requirements, reserve expectations and eligible occupancy types (primary, second home, investment) change over time, so confirm each on Rocket’s website or with a Rocket loan officer as of November 2026. I will not guess at them here, and you should not rely on anyone else’s summary, mine included.
The structural limitation is the one-company model. In a single application you see Rocket’s own products and pricing, not a comparison of other investors. For a standard salaried file with strong credit and a conventional property, that may be perfectly adequate. For unusual income or assets, confirm with any originator, Rocket included, how its guidelines treat your situation before you invest time in the process.
Pricing
Starting pricing is not fixed in advance for a jumbo loan. Rocket’s website explains what it charges, and the Loan Estimate you receive shows the actual figures. Loan size, credit profile, down payment, points and occupancy all move the cost.
Pros:
- Streamlined self-serve process
- Strong brand scale and technology
- One company from application to closing
Cons:
- No multi-lender comparison inside one application
- Less room to shop investors for unusual files
Best for: buyers with a clean, standard file who want one fully digital process.
How Do Jumbo Costs Compare: One Lender or Several?
The structural difference is simple. A single-company originator prices your loan on its own shelf. A broker can request terms from several wholesale investors and put them side by side. I make no claim that either route costs less; the only fair test is a line-by-line comparison of Loan Estimates for the same loan.
A loan is jumbo when it exceeds the conforming limit set by the Federal Housing Finance Agency. For 2026 the baseline one-unit limit is $832,750, with higher limits in designated high-cost counties, per fhfa.gov (confirm your county there). Here is the earlier example in cost format, using the same $1,000,000 loan:
- Principal and interest: $6,321 (Offer A) or $6,239 (Offer B)
- County property tax: $938 a month, assuming 0.9% of the $1,250,000 price; use your county assessor’s site for the real rate
- Insurance: $350 a month, assumed
- PMI if any: none, with 20% down
- Total monthly cost: about $7,608 (A) or $7,526 (B)
Illustrative only, not a quote. Offer B’s $10,000 point makes its total cost higher until about year ten. The CFPB’s Loan Estimate guide shows where to find each item. Compare these:
- APR, which folds in some fees
- Points and lender credits
- Origination charges
- Reserves required after closing
- How long you plan to keep the loan
Verdict: it depends on whether you will actually compare more than one offer. If you will, Dare to Compare and a broker gives you more to compare. If you will take one offer, a single digital process may be enough.
Which Handles Complex Jumbo Files Better: Self-Employed, Asset-Based and Second Homes?
Documentation is where jumbo files diverge. A salaried borrower typically verifies income with pay stubs and W-2s. A self-employed borrower usually provides tax returns, and some investors also offer bank-statement programs that look at deposits instead. Asset depletion is a concept where liquid assets are converted into qualifying income by a formula. Whether it is available, and how it is calculated, varies by investor, so I treat each as something to confirm with the specific investor, not assume.
Occupancy also changes the numbers. A second home or investment property generally brings higher down payment and reserve expectations than a primary residence. Fannie Mae’s Selling Guide sets out its eligibility rules for conforming loans by occupancy, but it does not govern every jumbo program, because jumbo guidelines belong to the individual investor.
That is the broker’s advantage: access to investors whose guidelines differ, so a file that does not fit one program may fit another. Rocket’s advantage is predictability. One company’s standardized underwriting is easier to anticipate if your file fits cleanly, and the digital tools for verifying income and assets can speed up a straightforward case.
I would be careful with any claim that one path “handles” complexity universally. Approval always depends on the file, the property, the appraisal and the investor’s guidelines at the time.
Verdict: for self-employed income, asset-based qualification or a second home with an unusual profile, a broker has more routes to test. For a clean W-2 primary residence, the two are close and the choice is about preference.
Process, Speed and Closing Certainty: App Experience vs Personal Guidance
Rocket’s convenience is real: app-based tracking, e-signing, and document upload at any hour. If you like handling everything on your phone without a conversation, that is a strength worth weighing.
My model is a different kind of certainty. One named person, me, handles conditions, appraisal questions and, if a file hits a snag with one investor, a switch to another. Timelines depend on the file, the appraisal and the lender, so I do not promise speed, only active management of the path.
The path I use keeps your credit safe until you are ready:
- Gather two years of tax returns (if self-employed), recent pay stubs or business documents, and two months of asset statements.
- Tell me the property type, occupancy, price and down payment.
- I review the file and the investors whose guidelines fit it.
- You complete the NoTouch Credit Pull soft pull pre-approval, which does not affect your credit score.
- With a clear path, you decide when a full application and hard inquiry make sense.
Pre-approval is subject to credit approval and underwriting guidelines, and a soft pull pre-approval is not a final approval.
Who it does not fit: if you want purely self-serve digital with no phone call, Rocket matches that better. If your property is outside Virginia, Florida, Tennessee, Georgia, DC, North Carolina, South Carolina, Maryland, Texas, Kentucky or West Virginia, I cannot arrange the loan.
Verdict: Rocket for self-serve convenience; a broker for hands-on certainty when the file is not routine.
Side-by-Side: Independent Broker vs Rocket Mortgage Model
Structural facts only, with no pricing:
- Lender access: a broker compares multiple wholesale lenders; Rocket offers its own products.
- Who funds the loan: a wholesale lender funds a broker-arranged loan; Rocket originates its own loans.
- Who services: varies with a broker-arranged loan and is disclosed to you; confirm Rocket’s current servicing practice on its site or Loan Estimate documents.
- Application channel: personal guidance plus a soft pull pre-approval for me; online app and dashboard for Rocket.
- Licensing footprint: 11 jurisdictions for me; Rocket is national, with its own state licensing to confirm.
- Advisory contact: one named loan officer for me; Rocket’s process is platform-led, with team support.
Reference data, each with its official source:
- 2026 baseline conforming limit: $832,750 for one unit; source: FHFA; as of 2026.
- National mortgage rate benchmark: the weekly Freddie Mac survey is published at freddiemac.com/pmms; it covers conforming loans, not jumbo, so check the current week’s figure there; updated weekly.
Jumbo Loan FAQ: Duane Buziak, Rocket Mortgage and Choosing a Path
What makes a loan jumbo?
A loan is jumbo when it exceeds the conforming limit set by the FHFA for the county. The baseline for 2026 is $832,750, and designated high-cost areas are higher.
Is Duane Buziak a legit mortgage broker?
Yes. Duane Buziak is licensed under NMLS #1110647, with 5.0 reviews and 2,000+ verified reviews across all platforms. You can verify his license on NMLS Consumer Access.
Who fits a self-employed jumbo borrower, a broker or Rocket Mortgage?
It depends on the file. A broker can compare investors with different self-employed documentation rules, while Rocket offers one standardized process. Confirm with any originator how your income will be calculated.
Does a Duane Buziak soft pull pre-approval affect my credit?
No. The NoTouch Credit Pull soft pull pre-approval does not affect your credit score. It is subject to credit approval and underwriting guidelines and is not a final approval.
Does Rocket Mortgage offer jumbo loans?
Yes, Rocket lists jumbo financing among its programs. Minimums, down payment and eligible occupancy change, so verify current terms on its website as of November 2026.
What is the difference between a broker and a direct lender?
A single-lender shelf offers that lender’s products. An independent broker can compare options across multiple wholesale lenders. A broker does not fund the loan.
Can a broker really access wholesale lenders?
Yes. Brokers are approved by wholesale lenders to submit loans. I shop your loan across multiple wholesale lenders and compare the terms with you.
What are jumbo reserves?
Reserves are liquid assets you hold after closing, often counted in months of housing payments. Requirements vary by investor, loan size and occupancy.
What documents should I gather?
Typically two years of tax returns or W-2s, recent pay stubs or business documents, and two months of asset statements. Your file may need more or less.
Can a second home be financed with a jumbo loan?
Often yes, though down payment and reserve expectations are usually higher than for a primary residence. Options and approval depend on the file and the investor.
Choosing Between Duane Buziak and Rocket Mortgage for a Jumbo Loan
- Choose Rocket Mortgage if your file is clean and standard and you want one fully digital process from application to closing.
- Choose Duane Buziak if you want several lenders’ jumbo terms compared on total cost, or your file is self-employed, asset-based, a second home or an investment property.
- Choose Duane Buziak if you want one named person managing conditions and appraisal issues, and your property is in a licensed jurisdiction.
- Choose Rocket Mortgage if you want self-serve convenience, or your property is outside my 11 jurisdictions.
For a straightforward salaried file, both can work well, and the difference may come down to how you like to work. For a complex file, I think the case for comparing multiple wholesale lenders is stronger, because the guidelines that decide approval and cost differ more from investor to investor.
Ready to see where you stand without putting your credit score at risk? Check today’s mortgage rates with a soft-pull pre-qualification and get personalized guidance from Duane Buziak, so you can move forward on your home purchase or refinance with confidence. Call 804-212-8663 to start your NoTouch Credit Pull soft pull pre-approval, subject to credit approval and underwriting guidelines.
2 Responses